Getting paid early sounds like an excellent problem. For a mortgage investor, it can be a nuisance with several decimal places. A homeowner refinances, the old loan disappears, and an investment expected to produce years of interest comes home ahead of schedule. The borrower has improved the household budget. Somewhere else, somebody has to redo a spreadsheet.
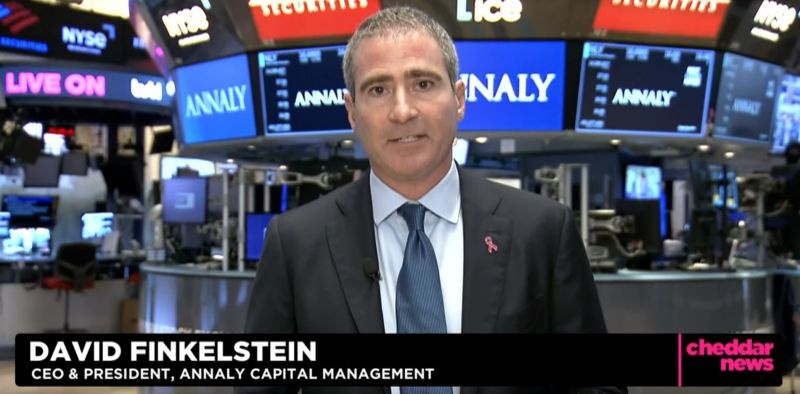
David Finkelstein works on that other side. As chief executive officer and co-chief investment officer of Annaly Capital Management, he invests in the financial machinery behind American mortgages. His career has carried him from trading desks to the Federal Reserve Bank of New York and then to the leadership of a publicly traded mortgage real estate investment trust. The same household decision can look quite different from each chair.
He became Annaly’s CEO on March 16, 2020, succeeding interim chief executive Glenn Votek. It was an unforgiving moment to inherit a company built around financial markets. Finkelstein arrived with experience of an earlier period when those markets had needed public intervention. He had spent four years inside the New York Fed, working on the purchase of the very securities that would become central to his private-sector responsibilities.
01 /An education on both sides of the trade
Finkelstein earned a bachelor’s degree in business administration at the University of Washington and an MBA at the University of Chicago’s Booth School of Business. He also holds the Chartered Financial Analyst designation. His professional background includes senior agency mortgage-backed securities trading positions at Salomon Smith Barney, Citigroup and Barclays. These are markets where understanding a bond means understanding the people whose payments sit underneath it.
From 2009 to 2013, he served as an officer in the New York Fed’s Markets Group, where he was the primary strategist and policy adviser for its MBS Purchase Program. That assignment placed mortgage trading knowledge inside a public institution with a different purpose from an investment firm. A trader asks whether a security is attractive at a price. A central bank must also consider how the market itself is functioning.
That distinction helps explain the range of his later work. Mortgage finance lives close to public policy: guarantees, central-bank decisions and the rules governing housing credit all matter to the investor. Finkelstein’s résumé joins practical trading experience with experience inside the institution implementing monetary policy. It gives his Annaly story a more specific beginning than the familiar procession of promotions.
- New York Fed Markets Group
- Joins Annaly’s agency trading desk
- Company-wide chief investment officer
- Chief executive officer and director
- CEO and co-chief investment officer
02 /Seven years from the desk to the corner office
He joined Annaly in August 2013 as head of agency trading. In February 2015, he became chief investment officer for Agency and RMBS. In November 2016, the company gave him a newly created chief investment officer position overseeing all investments and their related operations. The brief had expanded from a trading specialty to the allocation of capital across businesses.
Annaly then had agency, residential credit, commercial real estate and middle market lending operations. Finkelstein’s ascent therefore coincided with a broader investment menu. By the time he became CEO and a director in March 2020, he had already spent years helping manage the company’s investments. The promotion put the institution surrounding the portfolio under his charge as well.
In his appointment remarks, he praised the founders’ ability to “grow the Company through credit cycles and volatility.” The reference to cycles mattered. A mortgage business can look comfortable at one interest rate and awkward at another. His subsequent decisions would make a case for combining different housing exposures while reducing the number of unrelated businesses Annaly owned.
03 /The strategy that included selling things
One early change concerned how the company was managed. On July 1, 2020, Annaly completed the acquisition of its external manager and became internally managed. The nominal cash purchase price for the manager and its affiliates was one dollar, with no termination fee under the internalization agreement. The agreement had been announced before Finkelstein became CEO; he led the company when it closed. Even on Wall Street, one dollar still occasionally gets a speaking part.
Then came a narrower investment perimeter. Annaly completed the $2.3 billion sale of its commercial real estate business in 2021. In April 2022, it announced an approximately $2.4 billion sale of its middle market lending portfolio to Ares-managed funds. That transaction included assets on Annaly’s balance sheet and assets managed for others. It closed during the second quarter.
The disposals gave the company a clearer housing finance focus. Alongside agency mortgage-backed securities, Annaly developed residential credit and mortgage servicing rights, usually shortened to MSR. The company brought MSR onto its balance sheet in 2021 and began aggregating whole loans through its Onslow Bay correspondent channel that year. Finkelstein’s tenure included both exits and construction.
04 /Why the homeowner keeps changing the maths
The three businesses give him different ways to invest around a mortgage. Agency securities carry guarantees from Fannie Mae, Freddie Mac or Ginnie Mae. Those guarantees do not settle the question of what a security will be worth as interest rates, funding costs and repayment patterns change. Annaly selects assets and uses hedges to manage those exposures.
Residential credit adds loans and securities outside the agency market. Here the borrower’s ability to repay becomes a more direct investment consideration. Through whole-loan purchases and securitizations, Annaly can select mortgage assets and arrange financing around them. The operation turns individual loans into investments with different exposures and cash flows.
Servicing rights add another relationship with the borrower. They carry the obligation to service a loan in exchange for a fee. When borrowers refinance less often, that stream of fees can last longer. This can complement agency mortgage investments as repayment behaviour changes, although it brings its own valuation and operational risks. A portfolio manager is trying to fit those moving parts together while the homeowner is quite reasonably trying to get a better deal.
One loan. Different exposures.
Guaranteed mortgage cash flows; interest rates, financing and repayment timing still matter.
Loans and non-agency securities; borrower credit and asset selection enter the calculation.
Fees for servicing loans; refinancing changes how long the fee stream can continue.
05 /Capital needs company
Finkelstein’s explanation of the business often comes back to the arrangements that make the assets workable. At Annaly’s November 2024 investor day, he framed the discussion around scale, people, adaptability and efficiency. He also wanted investors to see financing, liquidity, risk oversight and policy alongside the portfolio. The supporting plumbing deserved time on stage.
The guest list reflected that breadth. Housing policy specialists Jim Parrott and Mark Zandi were scheduled to speak in a discussion moderated by Annaly’s Tanya Rakpraja. The event brought investment teams and policy into the same programme. A mortgage investor has reasons to care about both the next funding agreement and the next decision affecting the government-sponsored enterprises.
Partnerships also shape the servicing business. In October 2025, Annaly and Pennymac announced a relationship covering servicing and the purchase of mortgage servicing rights, with Pennymac handling servicing and recapture activities for the relevant loans. Recapture means bringing a borrower’s next mortgage back into the relationship when the existing loan is refinanced. Keeping that connection can matter to the value of a servicing book.
In a December 2025 conversation with HousingWire’s Diego Sanchez, Finkelstein discussed subservicing partnerships, growth and the rate environment. His public agenda had become a mixture of investing and coordinating capabilities held by other firms. Annaly could commit capital while partners supplied borrower-facing operations. The quality of those connections belonged in the investment calculation.
06 /From mortgage pools to a New York address
His institutional connections extend beyond Annaly. Finkelstein is vice chair of the Treasury Market Practices Group, sponsored by the New York Fed. The group works on the integrity and efficiency of Treasury, agency debt and agency mortgage-backed securities markets. He also serves on the Dallas Fed’s Financial Sector Advisory Council. Both roles keep his work close to the meeting point of markets and public institutions.
In June 2026, he joined the board of Breaking Ground, the New York supportive and affordable housing organisation. Its chair, Michael Franco, and chief executive, Brenda Rosen, welcomed his housing finance and capital markets experience. Finkelstein said he wanted to contribute that experience to the organisation’s housing work.
The appointment gives the housing theme a different scale. A mortgage portfolio combines thousands of household obligations into securities and servicing assets. A housing organisation has to create and sustain places for people to live. His board role links his financial expertise to that work in the city where he is based. The terminology changes; the need for dependable housing capital remains.
“support its mission to provide safe, stable housing”
David Finkelstein / on joining Breaking Ground, June 2026
07 /The next quarter still gets a vote
The figures published on October 20, 2026 put a difficult quarter beside the longer strategy. Annaly reported a third-quarter economic loss of 7.6% and book value of $17.86 per common share. Earnings available for distribution, a non-GAAP measure, were $0.80 per share against a $0.75 common dividend. Income generation and changes in portfolio value were telling different parts of the story.
One quarter, two measures
EAD is a non-GAAP measure. Common dividend: $0.75 per share. These figures measure different aspects of performance.
Those results followed a 5.5% economic return in the second quarter. The reversal is a useful reminder of the conditions under which Finkelstein works. Building several complementary businesses still leaves a mortgage investor exposed to financial markets. In his October remarks, he acknowledged the challenging period and emphasised discipline in capital allocation, leverage, liquidity and hedging.
His ambitions remain tied to the business he has assembled: investing across agency securities, residential credit and servicing rights, with enough flexibility to move capital as opportunities change. The record is available quarter by quarter, including the uncomfortable entries. Behind the acronyms sits the problem that has followed him through trading, policy and management: an investment’s future depends partly on what a homeowner decides to do next.
Keep reading. Keep watching.
Conversations, company updates and public work.
Annaly / leadershipDavid Finkelstein / LinkedIn & writingWatch / Power House conversationHousingWire / interview & episode notesWatch / economy and housing with SchwabRead / third-quarter 2026 resultsBreaking Ground / board appointmentTreasury Market Practices GroupHousingWire / YouTube channel