A mortgage does not end with the keys. It acquires payments, letters, rate changes and a growing history of human decisions. Someone has to keep that history straight. Phoebus Software has spent decades selling the systems behind this continuing administrative relationship, where the exciting outcome is often that an ordinary working day stays ordinary.
That is a substantial business to be in. In May 2024, Phoebus said assets administered on its servicing platform had passed £110 billion following new customer wins. Aston University’s September 2025 announcement put the total above £120 billion. The figure describes clients’ assets running through software. Phoebus supplies the machinery; the banks and lenders own or service the financial relationships.
The distinction matters. This is institutional fintech, bought by organisations that must keep accounts functioning through product changes, portfolio acquisitions and years of customer contact. Its customers include banks, building societies and specialist lenders. For most borrowers, the technology is several layers behind the name on the statement.
Client assets administered on the Phoebus servicing platform.
The history has to move, too
A lender replacing its software has an awkward inheritance: everything already recorded in the old system. A balance alone will not explain how an account arrived there. Phoebus’s migration API is designed to bring across transactions, notes, audit records and images, as well as the account itself. Clients can handle the work with assistance or have Phoebus manage it.
That makes migration expertise a commercial argument in its own right. A new system can look persuasive in a demonstration. Its usefulness becomes much easier to judge when staff can retrieve the information they need from an existing, complicated book of business. The unshowy detail is the product.
Phoebus’s 2023 impact report describes repeated trial runs before a transfer and experience with portfolios ranging from hundreds to hundreds of thousands of accounts. The lesson worth borrowing is the rehearsal: define what must survive, test the transfer and make the cutover the last step. A weekend migration is the visible finish, not a useful estimate of the whole project.
- 01 / UnderstandMap accounts and their histories
- 02 / PrepareClean data and rehearse
- 03 / TransferMove the agreed records
- 04 / ServicePut the information to work
One lender, seven weeks, some imperfect data
Keystone Property Finance offers a useful example. The specialist buy-to-let lender first put new mortgage completions onto Phoebus, going live in May 2021. Its subsequent back-book project covered approximately £275 million and took seven weeks, with the final transfer over a weekend.
The vendor’s account identifies an early obstacle: gaps in the source data. Cleansing, testing and workarounds were part of the job. Keystone staff were undertaking their first migration, supported by Phoebus; the teams even used WhatsApp during the cutover. The case describes the initial portal experience as reinforcing Keystone’s decision to bring its existing portfolio across.
The practical gain was control. Staff could input data and generate reports themselves instead of paying a third party for those tasks. That is a specific explanation of where savings can arise. It also exposes the condition behind the result: the lender must have people ready to operate the system.
The economics behind the interface
Capital Home Loans had a different scale of problem: roughly 57,000 mortgage accounts across multiple systems, manual work and limited automation. Phoebus’s published case study describes an implementation completed within 12 months, followed by the account migration over a weekend.
The reported outcomes include a 30% platform cost saving and a staffing requirement reduced from 50 to 36 full-time equivalents. Those are this customer’s results, with its particular starting point. They should inform questions about a business case, rather than become a universal savings forecast.
“Our legacy book was complex, with poor data.”
Matt Kimber, COO, Capital Home Loans
The broader commercial relationship is visible at Selina Finance. In August 2024, Phoebus announced a five-year servicing agreement with the second-charge lender. It said 15 weeks elapsed between the first conversation, user testing and contract finalisation. That interval measures the activities described; it should not be confused with the duration of every implementation.
These engagements show the shape of the business model: software accompanied by delivery work and an ongoing institutional relationship. The SaaS offering adds another delivery route. A May 2026 announcement appointed Alistair Scott head of delivery, with responsibilities covering new implementations and existing customers’ transition to SaaS.
Mortgages come in more than one flavour
Phoebus’s residential module covers conventional home loans, buy-to-let and secured lending. Equity release brings its own calculations and account requirements, including information relevant to vulnerable customers and arrangements involving powers of attorney. In buy-to-let, exposure-group functionality helps lenders examine relationships across borrowers, directors and portfolios.
The point is that a mortgage platform needs to understand the product being administered. A specialist lender is purchasing accumulated knowledge about account behaviour alongside the software. Commercial mortgages and specialist finance also have places in Phoebus’s module range, broadening its reach beyond ordinary household borrowing.
Pure Retirement illustrates the value of a sustained relationship. Phoebus’s historical case study describes work beginning in 2013 and collaboration on funding relationships, origination, servicing and APIs. By the period described around 2020, Pure had a £1.2 billion portfolio and an annual origination run rate above £500 million.
That history makes a persuasive reference for the supplier, but growth belongs to the lender too. Technology is one ingredient among funding, distribution, products and execution. The useful detail is the continuing adaptation: the two businesses worked on the connections and account capabilities needed as Pure’s operation expanded.
Savings, cash flows and the customer at home
On the savings side, Phoebus supports personal and business easy-access and term accounts. Its published functionality includes account opening after application completion, customer detail changes, withdrawals, closure and instructions when a term account matures. Staff can also manage the digital features from the servicing back office.
That connection between the customer’s request and the institution’s working record is the attraction. The self-service offering lets account holders inspect and update aspects of a loan without contacting the lender. Phoebus says the module can also work with another supplier’s servicing platform. A lender may therefore consider a narrower digital project alongside a larger replacement.
For institutions funding loans through securitisation, Phoebus supplies a separate module. It supports selecting accounts, configuring vehicles and setting cash-allocation rules. Its “waterfalls” determine the order in which money is distributed. Overnight processing and transaction analysis turn a complicated funding arrangement into repeatable operational work.
These are connected but different buying needs. A borrower wants an understandable account view. A servicing team wants usable records. A funding team needs cash flows assigned correctly. The appeal of a shared platform is that those jobs can draw on connected information, while each retains its own purpose.
A specialist with neighbours
Phoebus does not have to supply every surrounding application. Its API programme connects third-party systems to servicing, and its partner directory includes mortgage origination provider Mast, retention specialist Eligible and conversational technology supplier Webio. Rockstead adds consulting and due diligence expertise. That network gives buyers scope to assemble capabilities around the core.
It also puts Phoebus in a recognisable competitive market. Finova offers lending and savings servicing, including account administration, collections and customer portals. Feature overlap is real. A buyer assessing Phoebus should examine the fit of its specialist products, migration approach and integrations against the particular accounts it needs to run.
For a lender wanting only an application journey, that broader servicing capability may exceed the immediate requirement. For an organisation with poor records and little capacity to prepare them, an API cannot supply the missing understanding. These are practical limits of the approach, apparent in the preparation its customer projects describe.
Before the fintech label
The business began in 1989 within Heritable Bank and became independent in 1997. NorthEdge backed a management buyout in June 2019, supporting the existing leadership under Paul Hunt and further investment in the product offering. Its roots place it among financial software businesses that predate the contemporary fintech vocabulary.
There is a pleasing institutional footnote: Phoebus’s own history records its first external sale to the Bank of England in 1996. That timeline also records a Java redevelopment in 1997, hosting in 2011 and digital mortgage self-service in 2020. The software has had several technological lives already.
The people proposition is similarly concrete. Phoebus advertises hybrid working, private healthcare and a £350 annual wellbeing allowance, alongside a Developers’ Academy and leadership development. Its values spell DONE: Dedicated, Open, No Nonsense, Excellence. “No Nonsense” is a particularly testable promise when somebody is trying to move a loan book before Monday.
The next interface may be a conversation
In September 2025, Phoebus and Aston University announced a Knowledge Transfer Partnership to develop conversational AI for mortgage and savings servicing. The proposed work applies natural language processing, metadata generation and data mining to the problem of navigating complicated account information. It is a development programme, not evidence that every proposed capability is already available.
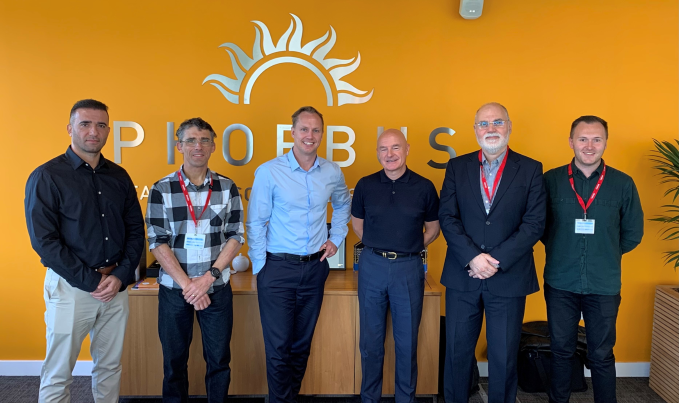
The announcement says Phoebus had already invested millions of pounds in modernisation. It identifies a familiar frustration: users spending time searching across screens. A conversational interface aims to make the underlying information easier to reach. Its eventual value will depend on the quality and usefulness of the answers it returns.
That brings the story back to the account record. However fashionable the interface becomes, a servicing system must help someone understand what happened, what is happening and what to do next. Phoebus’s most interesting claim on the market comes from years spent handling that continuity. The mortgage gets signed once. The work keeps arriving.
Follow the account
Explore Phoebus’s website, its product modules, customer stories and news and commentary.