After more than a decade around banking and fintech, Okiemute Avworhokai went to Y Combinator and discovered he had more learning to do. It is an appealing admission from someone whose job involves persuading other people to have confidence in him. The Miden co-founder could have presented the Winter 2024 batch as a stamp of approval. Instead, he described a revision of his own education.
“I was completely rebuilt from the ground up,” he wrote afterwards. In a business devoted to infrastructure, even the founder apparently required some construction work. The point of his account was practical: better questions, closer attention to what mattered, and help making the company intelligible to investors. He had arrived with experience. Experience, it turned out, still had homework.
Avworhokai, also known as Dom Okiemute, is CEO and co-founder of Miden. His company helps other businesses launch and manage card programmes and financial products in Sub-Saharan Africa. Much of its work happens behind the payment a customer sees. His career has taken him through the institutions, relationships and operational details that sit behind that apparently simple moment.
Before the API, the customer
His route into finance began outside the usual subjects. He studied agriculture at the University of Ilorin between 2008 and 2013. His early career included nursery operations at Nigeria’s Federal Ministry of Agriculture, followed by relationship management at Heritage Bank. Later roles included personal banking at ProvidusBank, business development and partnerships at Dash Nigeria, and co-founding Scenic Sentosa as chief operating officer.
The titles describe several views of a financial business. A relationship manager deals with the customer across the desk. A partnerships executive deals with the institutions a service depends on. An operating role brings the daily business into focus. Together, they help explain why Miden’s founder talks about the mechanics of getting a financial product into use.
Before Miden, he also founded a credit business focused on student loans. That venture disbursed more than $1.5 million over 18 months. It places him on the lending side of financial access before the infrastructure chapter. The student had to receive the money; the business had to make the transaction possible. A promise of access eventually needs an actual transaction.
By September 2023, he was discussing Tyrus Technologies, the company behind Miden, on Daniel Ose Edwin’s Growing Africa podcast. The conversation concerned reliable online card transactions across Africa. This was already his subject before the accelerator arrived. The later YC chapter gave him another way to work on a problem he had brought with him.
A small card, a long queue
Avworhokai co-founded Miden with Ini Udoh, its chief technology officer. Udoh brought his own banking and fintech experience, including work at First Bank of Nigeria, Heritage Bank and Mukuru. The partnership put commercial experience alongside technical experience in financial systems. Miden began with card issuing and processing, with a broader banking software stack as its ambition.
The opportunity was partly a matter of time. A business could have customers ready for a financial product and still face a lengthy bank integration before it could offer cards. Miden offered an API that businesses could use to launch virtual-card programmes within weeks. The attraction was straightforward: less time between deciding to offer a service and actually providing it.
In early 2024, Miden said it had issued more than 100,000 cards across four countries. By February of that year, Avworhokai described a company serving 25 businesses and processing about ₦3.5 billion a month. Those are snapshots of the early business, with a date attached. They capture the point at which the infrastructure began acquiring customers and a transaction history.
He also described a difficulty that money alone would not neatly resolve: finding people with the right local knowledge. “People with localized domain knowledge are scarce,” he said. A payment product has to work inside the market where it is used. Familiarity with the technology helps; familiarity with the institutions, practices and constraints around it matters too.
“We are currently profitable because we are lean and worked on our unit economics.”
Okiemute Avworhokai, March 2024
His explanation of the early business also had an accountant’s restraint. In March 2024, he said Miden was profitable, linking that position to a lean operation and its unit economics. It was a claim about that stage of the company, rather than a guarantee about every stage to follow. Still, it offered a useful counterpart to the growth figures. Customers and transactions were one part of his account; how the business made them work financially was another.
A simplified view of the original card programme. The business integrates the infrastructure into the service it offers its customers.
The awkward numbers are useful
In October 2024, Avworhokai was credited as an executive producer of Miden’s corporate-card adoption report. It surveyed 100 employees and business owners online. The sample matters: these findings describe respondents to that survey, rather than every Nigerian business. Within it, 62% said their businesses already used corporate cards. Adoption, however, did not finish the job.
Among card users, 56.45% reported merchant-acceptance problems. Other responses pointed to demand for stronger security, easier connections to accounting software and more detailed spending controls. There is a whole product agenda in that list. Issuing a card gets it into circulation. Making it useful requires attention to the places, systems and decisions surrounding the transaction.
The distinction suits a founder who has worked in customer relationships as well as operations. A finance team needs to know what happened after a payment, too. The transaction must become a record that somebody can reconcile. It is difficult to celebrate a modern financial product while spending the afternoon explaining it to a spreadsheet.
A card in use still has work to do
The awkward findings are valuable precisely because they survive the sales pitch. They describe work still to be done. For a founder building financial infrastructure, a successful transaction is one test; a customer’s ability to operate around it supplies several more. The report gives Avworhokai’s market a useful degree of specificity. The complaint has an address inside the product.
A table full of other answers
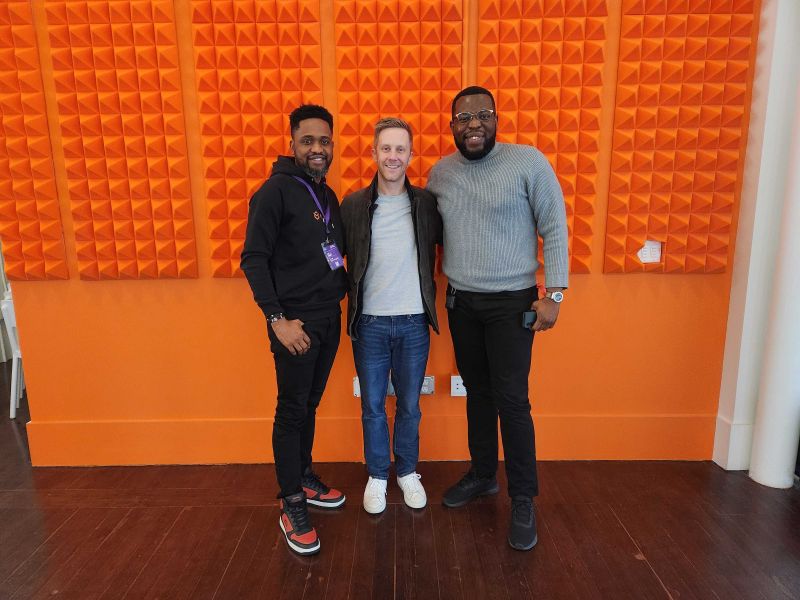
His account of YC makes room for the people who changed his thinking. Tom Blomfield was Miden’s primary partner. Avworhokai remembered explanations that continued until the detail made sense. He described Michael Seibel preparing for their first meeting by researching the industry, and Tyler Bosmeny helping with the pitch deck and investor introductions. Advice came with preparation and practical assistance.
His reflection also described a move away from vanity metrics. It is an especially useful concern in payments, where a large number can conceal several questions. What period does it cover? What does it measure? What does it cost to produce? The photograph of the founder smiling after the programme tells one story. His account of the work tells a more useful one.
Today, Miden presents a wider product range: card issuing, banking infrastructure, accruals and disbursements, treasury and core banking. Its website lists more than two million cards issued and more than $2 billion in processed volume. These are the company’s undated cumulative claims, visible in October 2026. They measure something different from the monthly transaction figures of its early days.
The wider range gives Avworhokai’s original ambition more places to be tested. Every additional service creates another part of a customer’s operation that must work. The attraction of an integrated platform is fewer awkward handovers. Delivering that attraction means making the connections useful in daily practice. The ambition grows; the customer still needs the payment to go through.
Miden has also put its name to a practical checklist about earning trust from the start, drawing on founders, engineers and operators from several businesses. Avworhokai appears on that project as its CEO. The subject brings the story back to the customer relationship. A financial service asks people to rely on decisions and processes they cannot always see. Each working interaction gives that relationship something firmer to stand on. A checklist makes the large word, trust, answerable to smaller decisions.
Another kind of infrastructure
Education appears elsewhere in his work. Through a partnership with Chess in Slums Africa, Miden supported 35 scholarships across school, tertiary and vocational programmes. The collaboration also supplied learning tools, including chess clocks, an abacus and a smart television. Here, access had a different set of practical requirements: equipment, tuition and somewhere to learn.
“Education is what is going to save us in Africa,” Avworhokai said. He praised the combination of vocational and academic learning. The partnership’s choices put some detail behind that preference: several educational routes received support. The connection to his earlier student-credit venture is visible without requiring a grand theory of his life. Education has repeatedly become part of the work.
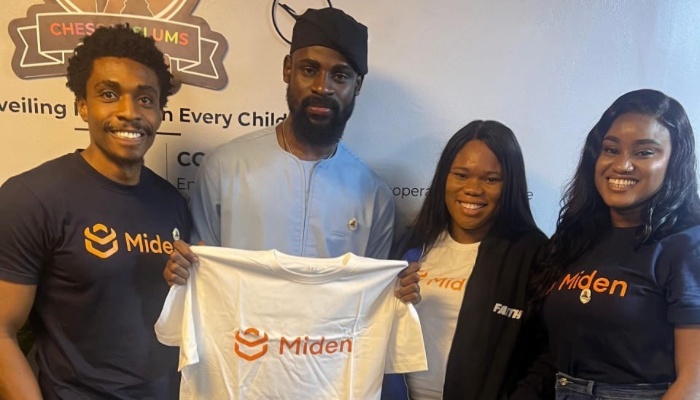
A later account of the Chess to Dream programme described 100 selected participants following outreach to more than 900 students. Its curriculum combined chess and literacy with STEM and digital learning. Alongside the company’s work helping businesses offer financial products, the partnership addressed another practical question: who gets the opportunity to take part?
That is a fitting place to leave a founder whose own public account makes room for another education. Avworhokai has experience, a company and an expanding set of responsibilities. He has also described the usefulness of being taught. For someone building the systems other businesses depend on, keeping that capacity alive looks like a sensible piece of maintenance.
More from Avworhokai’s working life
- Explore Miden’s products
- Avworhokai on LinkedIn · His publicly listed Twitter/X account
- Listen: the Growing Africa conversation about Tyrus
- Read his reflection on YC Winter 2024
- Explore the corporate-card survey
- The early Miden interview · The card-issuing business in 2024
- The scholarship partnership · Chess to Dream programme coverage
- Miden’s Y Combinator profile