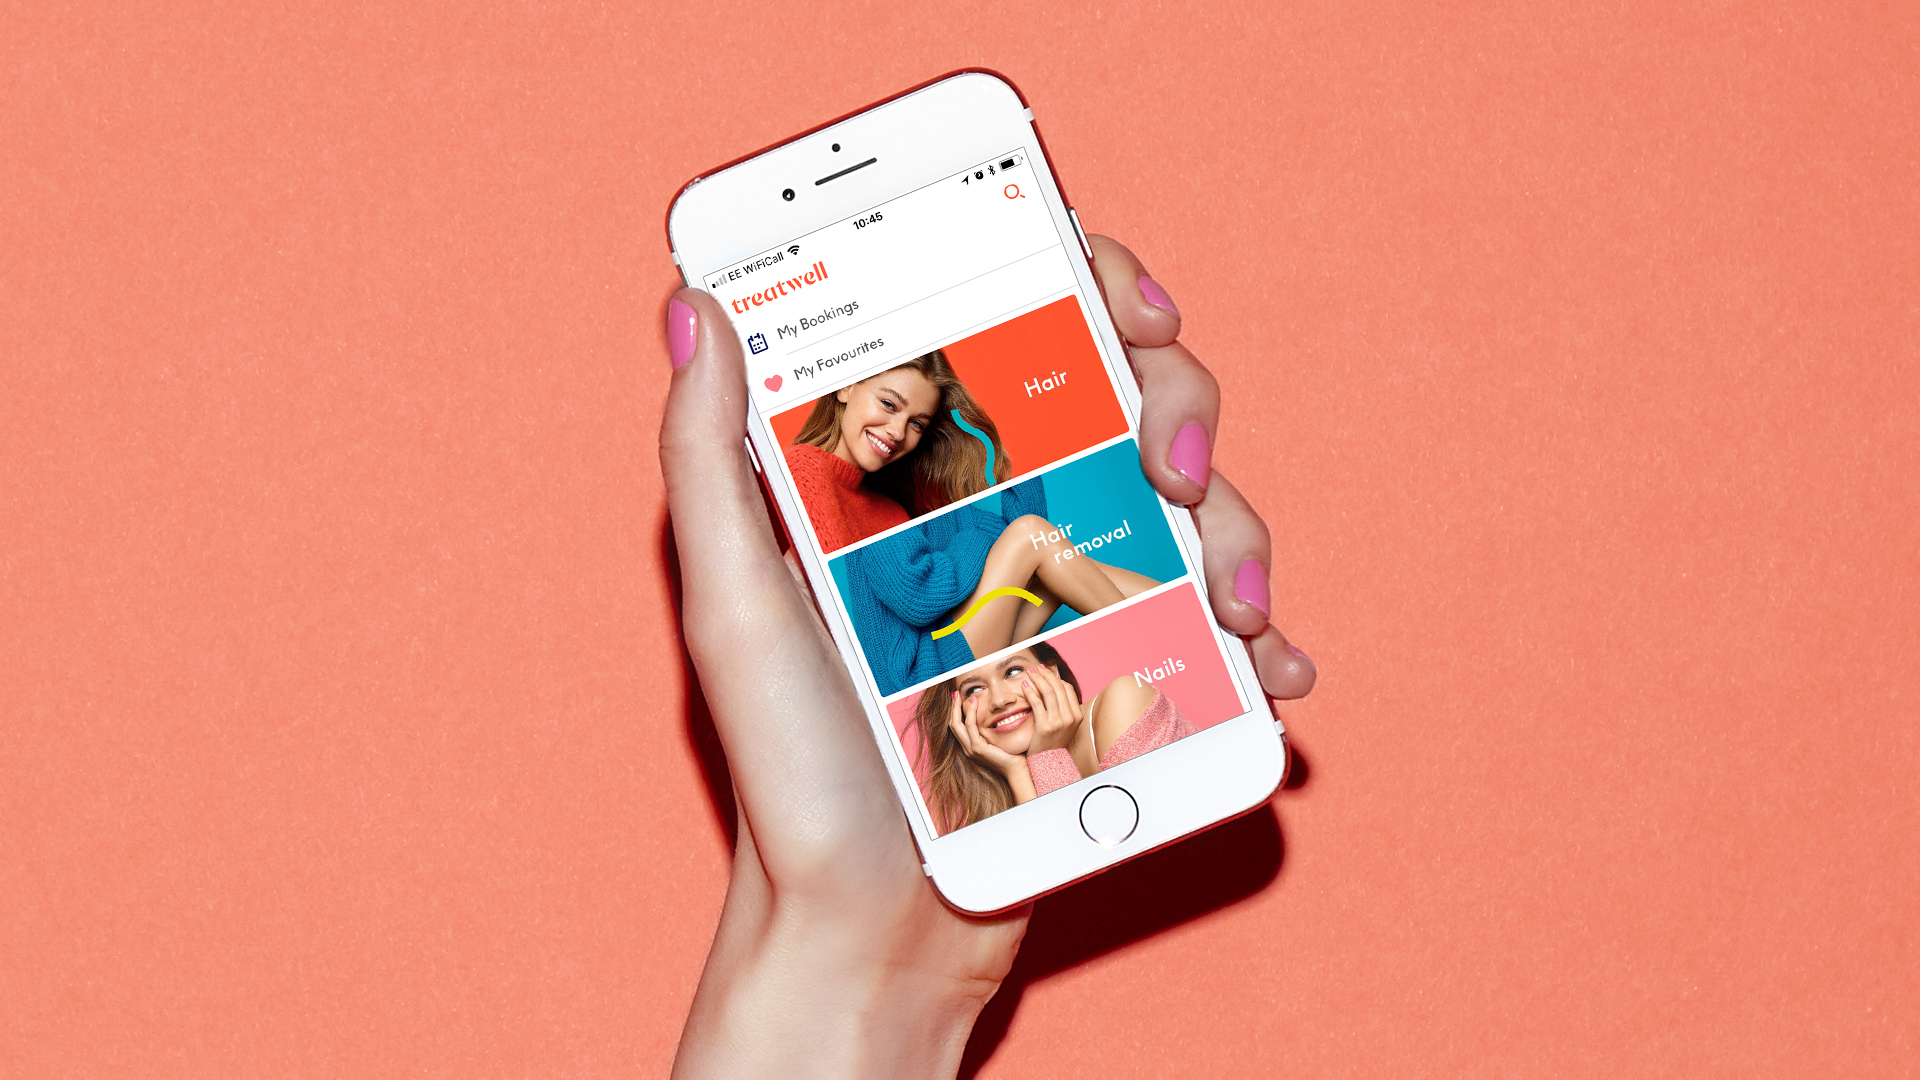
In 2012, a business backed by Eight Roads did something that would make most sales meetings go quiet. Treatwell, then known as Wahanda, stopped selling daily deals. Revenue fell by 75%. The business had been earning money from an activity that distracted it from the problem it wanted to solve: helping people book appointments at salons.
- Eight Roads backs technology and healthcare founders with equity capital and operating help.
- Its Fidelity roots stretch back to 1969; its network spans markets and specialist teams.
- Patience can fund a difficult pivot. It cannot make every investment work.
Treatwell offers a useful way into this investor’s story. Venture capital is usually explained through winners and valuations. Here, the revealing number measures money deliberately surrendered. In Eight Roads’ account, the deals irritated merchants and consumed sales effort. Dropping them freed the team to concentrate on bookings. By 2014, repeat rates were improving and acquisition costs in core cities were falling. Expansion followed evidence that the model worked.
Before the name, the habit
Eight Roads traces its lineage to Fidelity Ventures, which began investing from Boston in 1969. Early investments included MCI, Continental Cablevision and Atari. Long before today’s software vocabulary, the organisation was financing businesses that changed how people communicated and entertained themselves.
In 1999, that lineage reached Alibaba. Daniel Auerbach met Jack Ma in the apartment where developers were building the company. Eight Roads’ retrospective describes a five-hour conversation, followed by participation in Alibaba’s Series A. The dot-com crash then forced office closures and spending cuts. The famous outcome came much later: Alibaba’s New York listing in 2014. Between the initial conversation and the IPO sat fifteen years of company building.
The organisation also changed. In September 2019, Eight Roads completed its demerger from Fidelity International. Its explanation distinguished a conventional financial-services business serving external clients from a proprietary investment business backing growing companies. Financial backing from the Fidelity network continued. Independence and continuing family connections could coexist.
“navigate at our own speed”Eight Roads, explaining its 2019 demerger
What the cheque actually buys
Eight Roads’ offering has two parts: ownership capital and help with the work that follows. Its investees are founders and businesses, rather than ordinary customers buying a subscription. The economic objective is familiar venture investing: acquire equity, help the company become more valuable, and eventually realise value through a sale, listing or other liquidity event.
The details depend on the team and fund. Its fourth European and Israeli fund, announced in October 2021, contained $450 million. It targeted companies that had established product-market fit, with initial investments of $5 million to $50 million. This was a scale-up proposition: help a business with evidence of demand build a larger organisation around it.
Announced fund sizes in US dollars. Separate pools, not investment returns.
In May 2022, Eight Roads announced a dedicated $250 million India healthcare and life sciences fund. The plan was minority investments in 15 to 20 companies, with individual investments reaching $40 million. Its remit covered life sciences, healthcare services, consumer health and digital health. Those categories demand different kinds of expertise; a laboratory and a consumer app do not share a development calendar.
A passport needs local knowledge
“Global network” is easy to print. Its value appears when someone can answer a specific question. Eight Roads’ Venture Partner Divesh Dhawan, for example, works with portfolio companies on talent strategy and hiring. That is a concrete problem: the people who got a company started may need colleagues with different experience to manage its next stage.
The firm’s published commercial advice is similarly practical. Establish a working model at home, understand customers abroad, then choose deliberately between direct selling and local partners. Its founder discussions describe partners opening doors in relationship-driven markets, while remote selling can suit some lower-priced products. Geography changes the sales method. A successful pitch in one country does not automatically travel.
Healthcare adds a more hands-on example. Eight Roads and its US sister fund, F-Prime, studied biologics manufacturing in China before helping establish Innovent. The original idea centred on contract manufacturing. The thesis shifted toward developing medicines for China’s own patients as the team examined local needs and changing regulation. This was work done before there was a finished company to put in a portfolio brochure.
That distinction matters when judging expertise. A software investor may help redesign a sales organisation. A healthcare investor may need to understand manufacturing standards and the route from research to treatment. Eight Roads operates across both worlds. For founders, the relevant question is which people will actually work on their problem, and whether those people bring experience that the founding team lacks.
Patience still has a price
There are exits worth celebrating. PayPal completed its acquisition of Paidy in October 2021, after announcing a price of approximately $2.7 billion. Eight Roads counted the Japanese payments company among its investments. That transaction price describes the company’s sale; it does not tell us Eight Roads’ proceeds or investment return.
There are also uncomfortable entries in the record. Eight Roads’ 2021 fund commentary celebrated Cazoo’s rapid journey to a public listing. In May 2024, three Cazoo UK companies entered administration. A long time horizon cannot rescue every business model. Cash requirements, operating costs and access to further funding still matter.
Nor is an investor’s map permanent. In October 2025, Eight Roads told Moneycontrol it had realigned toward Asia and Asia-led cross-border businesses, restructuring teams accordingly. Its website continues to describe a global platform. Founders should distinguish that network’s accumulated reach from where the firm is directing new investment attention.
The questions worth copying
For a founder considering Eight Roads alongside firms such as Accel or General Catalyst, a useful comparison starts below the brand name. Which partner understands the business? Who will help hire? Which introductions match the next market? How much uncertainty can both sides tolerate before changing course? These questions are particularly useful when the next milestone is operational: recruiting a leader, proving a sales channel, or getting a product ready for a regulated market.
Eight Roads’ own scale-up writing asks founders to examine market size, sales repeatability, product differentiation, team alignment and funding horizons. Those are portable questions, even for someone who never takes venture capital. The Treatwell episode adds a sharper one: which revenue would you surrender to build the business you actually want?