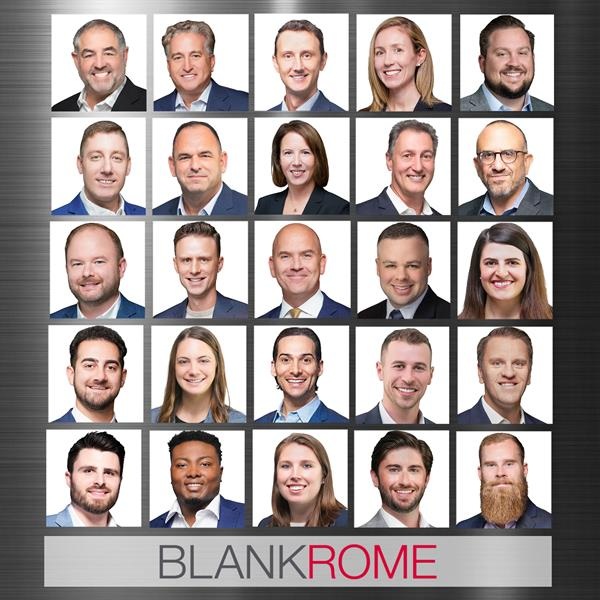
On May 1, 2024, twenty-five lawyers changed firms. They did not scatter into twenty-five separate adventures. Burns & Levinson’s corporate and finance team moved together to open Blank Rome’s Boston office. Thirteen partners, twelve associates, a new name on the announcement. The striking detail was the continuity: a departure could preserve a team while dismantling the institution that housed it.
- Burns & Levinson sold legal counsel across business and private life.
- Its specialist teams became attractive recruits for larger firms.
- After departures and merger talks, it announced its wind-down in September 2024.
For a client, that distinction matters. A law firm promises institutional memory, familiar judgment and someone who knows where the awkward documents are buried. Much of that value resides in people. The Burns & Levinson story asks a question that applies well beyond lawyers: what keeps a business intact when its useful parts can leave together?
A partnership with portable parts
Thomas Burns and Larry Levinson established the Boston firm in 1960 with William Clancy and Robert Weinstein. Four lawyers became a practice offering business law, litigation, intellectual property, real estate and private-client services. Its founding principles emphasized accessibility and responsiveness. These were ordinary promises with a demanding practical requirement: know the client well enough to answer the right question.
Expansion often arrived in groups. A dozen attorneys from Peabody & Arnold joined in 2002. Thirty-five from Perkins Smith & Cohen followed in 2006, deepening science-and-technology expertise. Bringing in an established team could add experience and relationships together. Years later, the same portability would work in the opposite direction.
The client who stayed from birth to sale
Consider Crossix Solutions, the patient-data and analytics business. Burns & Levinson represented it from its founding in 2005 through its $430 million sale to Veeva Systems in 2019. Partners Gil Breiman and Mark Manning led the transaction. Tax, employment, intellectual-property and regulatory specialists supported the deal.
That is the full-service model at its most intelligible. Formation becomes financing; financing becomes commercial agreements; eventually, a buyer arrives with questions spanning several legal disciplines. A client can assemble separate advisers at each stage. Keeping counsel across those stages offers a different bargain: less explaining the past whenever the next problem appears.
The customers were not exclusively companies pursuing exits. Families needed estate plans, trustees needed advice, and spouses needed representation in divorce. The firm’s lawyers addressed blended-family planning and elder financial exploitation. Boston College Law School also reported Ellen Zucker’s representation of surgeon Dennis Burke in a $13 million wrongful-termination settlement in 2019. The range included protecting livelihoods as well as completing transactions.
Cannabis needed bankers, too
The cannabis practice made that business-first approach particularly visible. Operators needed corporate structures, loans, acquisition agreements and a route through financial distress. Burns & Levinson worked on the less photogenic machinery behind the industry: who lends, what security supports the loan, and what happens when repayment stops.
Its reported 2023 work included Needham Bank’s $40 million refinancing of AYR Wellness and a Massachusetts cannabis receivership concerning a default exceeding $22 million. Those figures describe client transactions and debt, rather than revenue earned by the firm. In January 2024, Law360 named the group one of five Cannabis Practice Groups of the Year.
A map of the practice’s work, not a prediction of every client’s path.
The firm also gathered the market around a conference table. Its seventh annual State of the Cannabis Industry Conference, held in October 2023, featured lenders and operators; Needham Bank and HUB International were gold sponsors. For another specialist service business, the useful idea is simple: convene people whose problems intersect. Expertise becomes easier to demonstrate when customers can discuss the actual obstacles together.
The bill behind the relationship
A public Audacy Atlas engagement letter supplies a rare glimpse of the economics. For real-estate purchase-and-sale negotiations in June 2023, partner Leslie Muldowney listed an hourly rate of $725. The attached general schedule, effective that January, ranged from $520 to $1,000 for partners and $350 to $675 for associates and patent agents, with expenses additional.
This was professional time sold under engagement-specific terms. The price made sense when coordination and experienced judgment mattered enough to justify it. For a routine, narrowly defined task, assembling several specialists could be an expensive way to obtain a small answer. Breadth earns its keep when the problem actually crosses boundaries.
A team could move. A partnership could not.
In April 2024, four automotive partners joined ArentFox Schiff. The May corporate departure followed; nine family-law and probate-litigation attorneys also headed to Bowditch & Dewey. In June, ArentFox Schiff added another seventeen-person technology and life-sciences group, including lawyers and patent specialists. Different buyers wanted different pieces.
The departing corporate lawyers described broader capabilities as part of Blank Rome’s appeal. In May, Frank Segall told Massachusetts Lawyers Weekly:
“But we knew this was the right decision for our group, which is truly like family to us.”Frank Segall, May 2024
Leadership’s explanation of the final decision was more complicated than a shortage of offers. Managing partner Paul Mastrocola acknowledged governance, compensation and support discussions. The remaining partnership explored mergers but concluded that their economics, timing and complexity did not work for its varied practices. On September 27, it announced an orderly wind-down after sixty-four years.
Former partner Brian Bixby later told The American Lawyer that compensation disagreements preceded departures and that declining partner numbers triggered a credit-line default. That is an attributed account, not a complete financial diagnosis. It nevertheless points toward the distinction between having desirable practices and maintaining a viable partnership.
McCarter & English and Barclay Damon subsequently welcomed groups of lawyers. B&L Asset Management also found a new owner in October. The practical lesson is an inference from this sequence: build specialist teams and durable client relationships, then make staying together worthwhile. That approach depends on agreement about rewards, governance and the firm’s future. Clients could still find the lawyers; the partnership could no longer keep its parts in one place.
Historical firm website · Historical LinkedIn profile · Facebook archive · Twitter / X archive · CannaBusiness writing · The Blank Rome team announcement · The Barclay Damon move