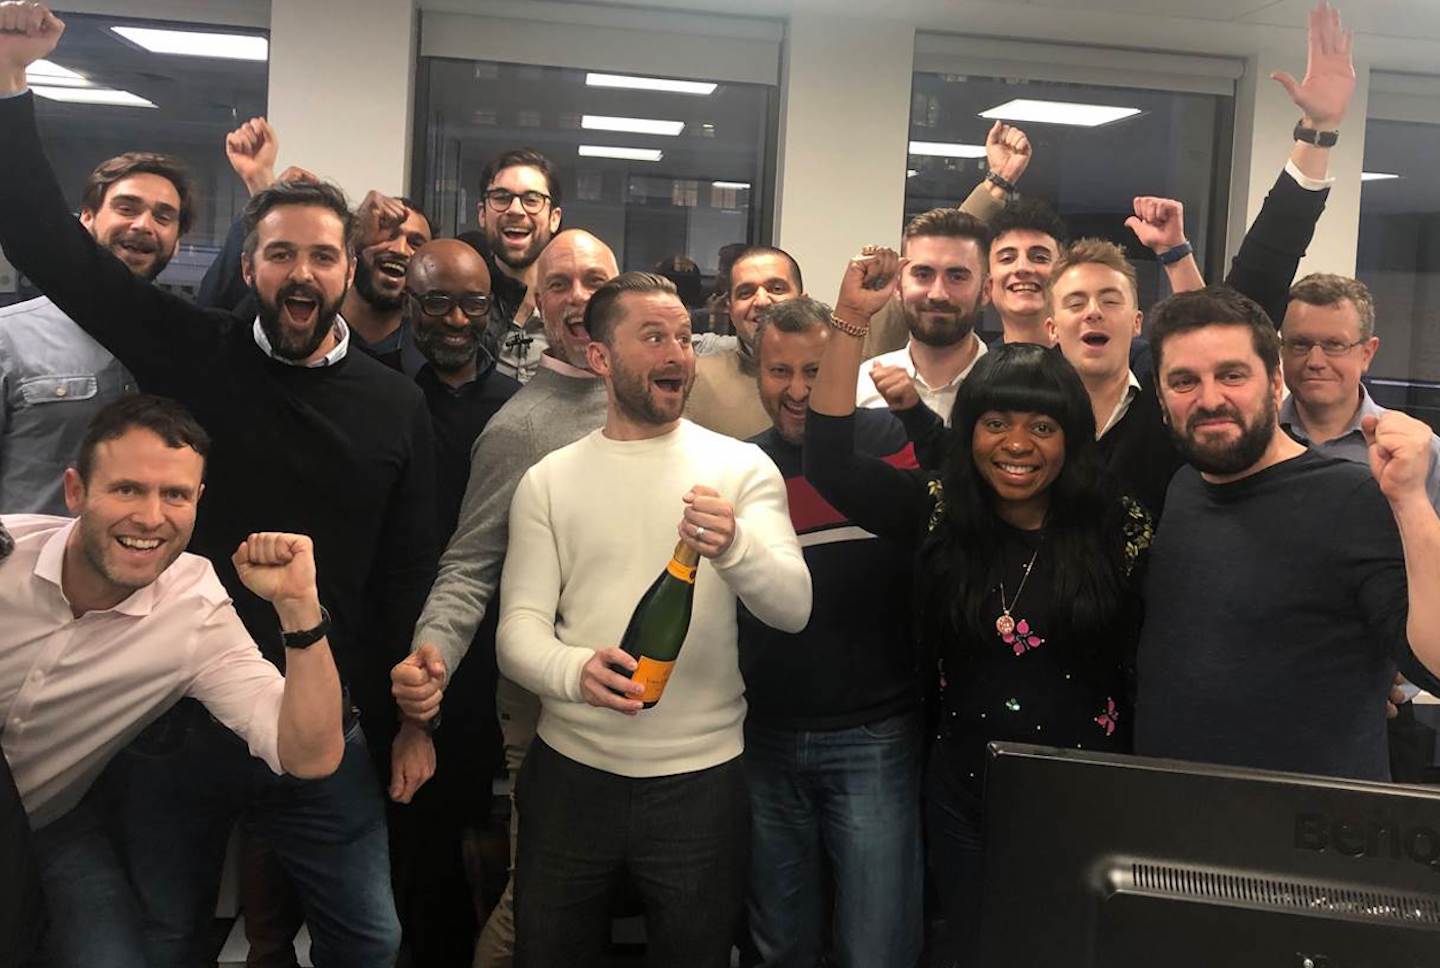
The photograph is wonderfully human for a company selling automation. Arms are raised. Faces are grinning. Jos Evans stands near the middle with a bottle in his hand. AiX’s team is celebrating a trade, and the machine that helped make it happen gets none of the champagne. Published in February 2020, the picture catches the reward at the end of a difficult software project: something that had been described, financed and engineered had actually worked.
AiX built an artificial-intelligence broker for the conversations behind institutional trades. A trader could communicate an order through a chat interface; software would negotiate and match it with another participant. In May 2021, Blockchain.com acquired the business to help develop its institutional offering. Between those two moments sits a useful business story about how much work hides behind a deceptively simple interface.
A broker with a complaint
Evans came to the problem from inside the trade. He had worked as a trader and broker, built a brokerage called Red Ops and sold it. In AiX’s 2017 launch announcement, he took aim at interdealer brokers, arguing that their service was expensive and opaque. His proposed remedy was a chatbot that could perform brokerage tasks across cryptocurrency and conventional financial markets.
The target was specific. Interdealer brokers help professional counterparties find one another and agree transactions. AiX wanted to automate the conversation as well as the search for a price. Its competitive reference point was the established brokerage business, with firms such as TP ICAP, BGC and Tradition, rather than a consumer app for watching bitcoin wiggle up and down.
The origin also contained a useful coincidence. Evans had invested personally in Rainbird, the reasoning-technology company. Seeing what that software could do helped prompt the brokerage idea. DigFin’s early reporting described training work with trading-message transcripts and a stubborn obstacle: different desks used different language for the same thing. Before the machine could negotiate, it had to understand the humans.
One chat window, several jobs
AiX’s product made sense for people already trading through messages. Pre-launch reporting described access through Telegram or Symphony after customer checks. The proposed advantage was anonymity between market participants, alongside automated negotiation, credit checks and the electronic transmission of trade details to settlement infrastructure. That was a workflow proposition: fewer manual handoffs between an expression of interest and a completed transaction.
For a professional trading desk, the appeal is easy to picture. An order can involve several conversations, changing prices and counterparties with different appetites. A useful assistant must keep those details straight. The customer is paying for reliable coordination as much as for the ability to type a sentence. A polished answer has little value if it carries the wrong size or price into the next step.
Rainbird’s account of the project explains the mechanism. Its team worked with AiX to encode trading expertise in knowledge graphs, including concepts such as liquidity and volatility. The engine could assess proposed trades against market information obtained from external data services, then return a recommendation through the chatbot. The emphasis was on reasoning that could be inspected and an audit trail that could explain a decision.
- 01AskA trader expresses an order in chat.
- 02NegotiateAiX evaluates and matches interest.
- 03SettleConnected infrastructure completes the transfer.
That distinction matters for anyone studying the company today. AiX’s documented system combined natural-language interaction with specialist trading logic. Its value depended on the information, permissions and execution machinery around the conversation. Reading its history as a story about a clever text box would miss most of the product.
The token sale that stayed a plan
In 2017, AiX outlined an ICO intended to raise as much as $200 million. That sale did not go ahead. Evans later told DigFin that the company could not obtain explicit British regulatory approval and decided the future risk was too great. By February 2020, the publication reported $8 million raised through seed and Series A financing, supporting 35 staff, including 26 programmers and engineers.
“Doing an ICO wasn’t worth the future risk to the business.”
Jos Evans · DigFin · February 2020
The distinction between those numbers is essential: one was an abandoned fundraising target; the other was reported financing. Neither is a customer price or an audited development bill. AiX’s business proposition centered on brokerage commissions and the possibility of charging less through automation. Its early announcement promised reductions of up to 95 percent, a sales ambition that should be read as a claim rather than a measured customer result.
The practical lesson is about keeping the product separate from the funding fashion. AiX changed how it intended to finance development while continuing to pursue an automated broker. A founder can copy that decision process: ask whether a financing mechanism introduces obligations or uncertainty that make the underlying business harder to build.
A trade agreed is not a trade settled
The engineering bottleneck was settlement. DigFin reported that automating the movement from negotiation through execution and settlement took two years, with the post-trade work especially difficult. Crypto lacked the familiar clearing arrangements Evans knew from derivatives. Connecting human and electronic liquidity into one working process took time.
The February 4, 2020 launch gave that process a concrete demonstration. GSR Markets and DV Chain traded bitcoin against dollars through AiX, and Zero Hash handled settlement. The announcement also named Blockfills and Trigon Trading among participants that had come aboard. These were professional trading businesses, the sort of customers for whom quoting, booking and safely completing a transaction belong in the same conversation.
AiX had announced an earlier AI-brokered crypto trade in June 2018 between Rockwell Capital Management and TLDR Capital. That demonstration and the 2020 platform launch are separate milestones. The earlier announcement emphasized simultaneous conversations and an auditable record; the later one identified the settlement provider and a wider group of market participants.
Rockwell Capital Management ↔ TLDR Capital
GSR Markets ↔ DV Chain
Settlement: Zero Hash
For a buyer evaluating comparable technology, that sequence suggests a sensible test. Follow a transaction all the way through, including what happens after both sides agree. Ask which party performs each task, what information crosses each boundary and where an exception lands. The cost of a manual rescue can quickly spoil the economics of an automated conversation.
Bondsai: an ambition beyond bitcoin
AiX’s interest in traditional assets produced an unusually memorable product name. In April 2019, it announced Bondsai, a proposed conversational broker for bond issuance and secondary trading. Working with XinFin, the company described a market for tokenized infrastructure bonds, connecting institutions to financing associated with power, water and transportation projects.
The plan cast AiX as a syndicate lead linking market makers, brokers, banks and investors. XinFin’s own announcement described integration with its test network and the creation of new and secondary markets. This was a broader ambition than automating a crypto quote: use the brokerage technology to help organize distribution and subsequent trading of financial instruments.
Those announcements describe intended activity. Their projected issuance and volume figures belong to the proposal, not to a tally of completed business. Even so, Bondsai is revealing. Evans’s target was the negotiated transaction itself, a process he hoped could travel between asset classes. Bitcoin offered a place to put it to work; infrastructure bonds represented another proposed destination.
Sell the machinery, join the institution
Another route to market appeared in March 2020, when DACX announced an OTC desk using AiX’s negotiation and matching technology and Zero Hash for post-trade settlement. DACX described a service for institutional, corporate and wealthy individual customers seeking larger trades away from open-market exchanges. AiX could therefore sit inside somebody else’s customer offering.
That arrangement illustrates where the company fitted in the market. A trading service needs customers, liquidity, a way to agree prices and a way to complete transfers. AiX supplied a specialist part of that operation. Its partners supplied other parts. For a desk operator, adopting the technology meant evaluating how those pieces worked together, not merely whether the chatbot sounded convincing.
Blockchain.com’s May 2021 acquisition brought AiX into a larger institutional business. The announcement emphasized the negotiation and matching engine, alongside the team’s engineering, trading and operational experience. It highlighted Evans’s derivatives background and chief operating officer Taylor Cable’s years at Moore Capital Management. The acquired asset included people who understood how a trading desk actually functions.
The purchase price was undisclosed. Blockchain.com presented the transaction as part of its institutional expansion, bringing in products and expertise through acquisitions. That gives the ending a clear commercial shape: a specialist supplier became part of a broader financial platform. The transaction itself does not establish that every earlier market-expansion forecast came true.
The useful idea inside the chat window
AiX’s experience offers a practical way to judge an AI business. Start with the expensive coordination problem. Put industry knowledge into the system. Make the handoffs visible. Measure success at the end of the customer’s task, after the message has been interpreted and the transaction completed. The familiar interface helps only when the less visible machinery earns the customer’s trust.
There are demanding conditions attached. Participants must supply usable information and real trading interest. The product needs access to appropriate counterparties and settlement arrangements. Ambiguous instructions need resolution before they become commitments. A system that negotiates efficiently cannot, by that fact alone, create liquidity or make an unwilling counterparty trade. These are limits inherent in the brokerage job AiX chose to automate.
The office photograph is a fitting last word. A working trade gave the team something specific to celebrate. For anyone building business software, that is a useful standard of evidence: a customer task completed, with all the awkward steps included.